01
AML & Transaction Monitoring
Excessive false positives, static detection rules, emerging laundering typologies, mule networks and complex fund flows that remain hidden across individual transactions.
Turning financial signal out of the noise.
Case File // RR-2026 — Technology Leader
Rajarshi Ray leads AI, Machine Learning and Financial Crime Compliance programs for Tier‑1 banks worldwide — 20+ years taking rule‑based AML into AI/ML‑driven detection, without losing a single SAR.
His solutioning spans the full compliance lifecycle: Sanctions and watchlist screening, real-time transaction and customer screening, Fraud detection across Cards, Markets and Brokerage, and end-to-end KYC onboarding — increasingly powered by Deep Learning, Generative AI and Agentic AI, with Graph Analytics driving entity resolution across it all.
Case File // 01 — The Current Landscape
Exploring the critical challenges facing financial institutions across AML, KYC, sanctions screening, regulatory reporting and fraud detection — and how intelligent technology can transform financial crime prevention.
Financial crime is evolving faster than traditional controls. Banks must balance detection effectiveness, operational efficiency, customer experience and regulatory accountability.
01
Excessive false positives, static detection rules, emerging laundering typologies, mule networks and complex fund flows that remain hidden across individual transactions.
02
Incomplete customer data, manual onboarding, complex beneficial ownership, inconsistent risk scoring and delayed identification of changing customer risk.
03
Name-matching false positives, aliases, transliteration, delayed watchlist updates, adverse media complexity and missed connections between related entities.
04
Data-quality errors, structuring detection, reporting deadlines, fragmented evidence and the challenge of producing accurate, consistent and defensible narratives.
05
Social engineering, account takeover, synthetic identities, deepfake-enabled scams, payment fraud and the movement of fraud proceeds through mule networks.
06
Growing investigation backlogs, disconnected systems, manual evidence gathering, inconsistent dispositions and limited feedback from case outcomes.
07
Changing regulations, cross-border requirements, model validation, audit findings, evidence traceability and the need for explainable decisions.
08
Legacy platforms, inconsistent data, duplicate identities, siloed customer intelligence and the difficulty of building a unified view of financial crime risk.
09
Trade-based money laundering, cross-channel criminal networks, crypto-related exposure and rapidly evolving techniques that evade conventional controls.
Case File // 02 — Why Transformation Matters
The objective is not simply to generate more alerts. It is to identify meaningful risk earlier, improve investigator productivity and create reliable regulatory outcomes.
A
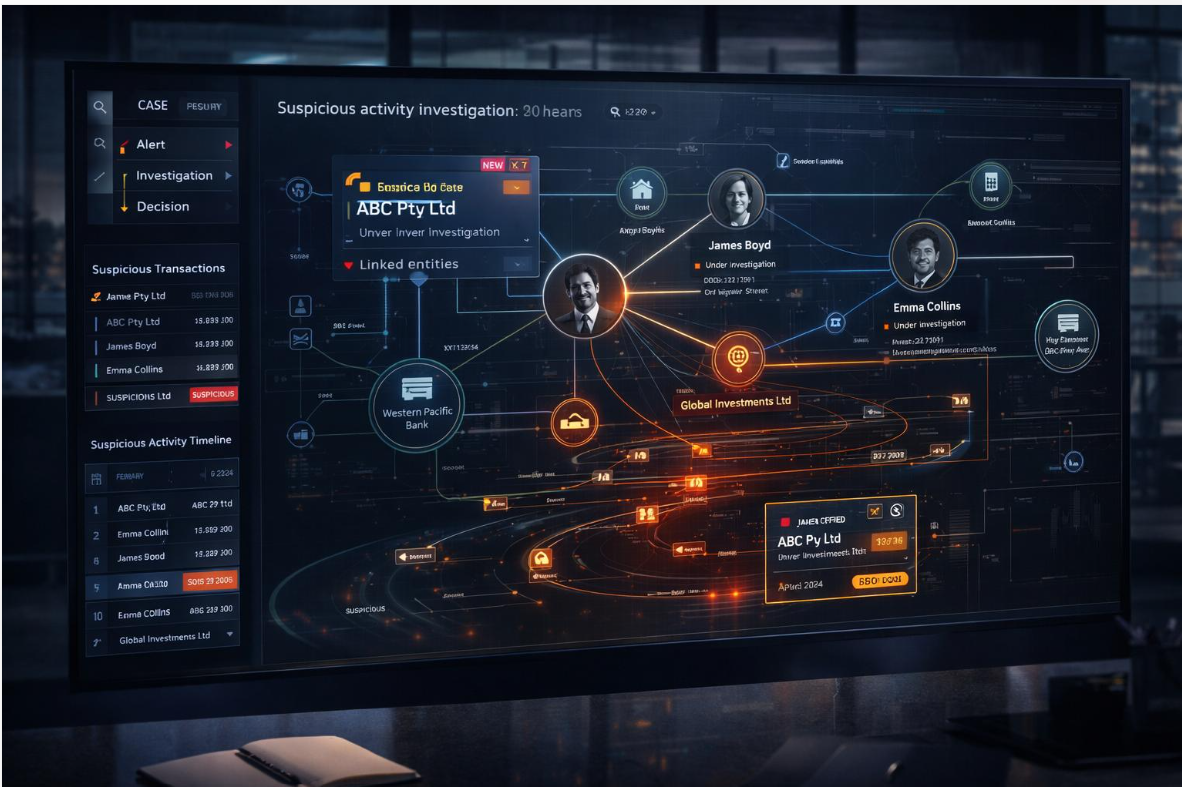
Improve alert relevance and prioritize cases using risk, context and historical outcomes.
B
Link customers, accounts, transactions, devices and investigations across systems.
C
Reduce manual evidence collection and support clear, auditable investigation decisions.
Case File // 03 — Technology & Innovation
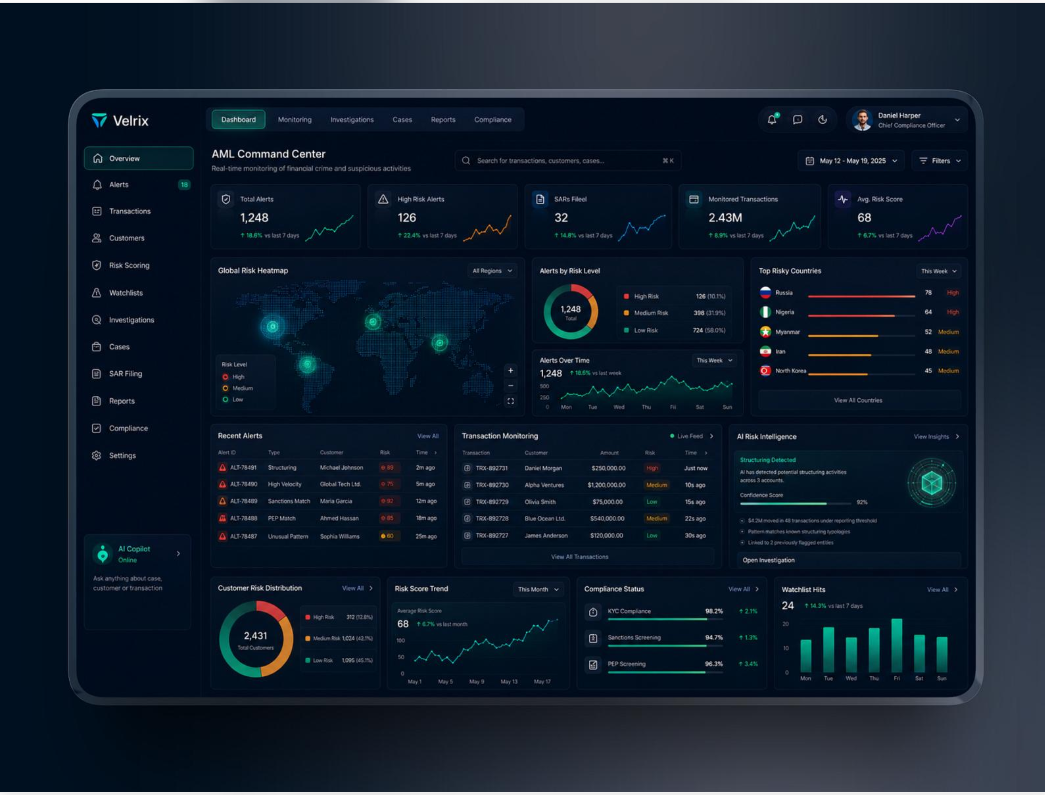
Combining established compliance controls with machine learning, graph intelligence and responsible generative AI.
01
Rank alerts using behavioural patterns, risk indicators and validated investigation outcomes.
02
Discover connected accounts, circular flows, indirect relationships and suspicious networks.
03
Identify unusual customer behaviour, transaction sequences and potential new typologies.
04
Combine KYC, screening, transactional behaviour and historical case information.
05
Summarize cases, surface related investigations and explain transaction patterns with supporting evidence.
06
Generate structured narratives from validated evidence, with human review and auditability.
Case File // 04 — Implementation Strategy
A phased approach to improving financial crime controls while maintaining regulatory accountability.
Measure data quality, alert performance, scenario coverage and reporting gaps.
Unify customer, account, transaction and investigation information.
Introduce validated models, graph analytics and anomaly detection.
Automate evidence summaries and support controlled narrative drafting.
Monitor performance, explainability, drift, auditability and outcomes.
Case File // 05 — Outcome-Driven Transformation
Every FCCM innovation should be evaluated against a defined baseline, representative data and appropriate governance.
01
Recall, precision, confirmed-risk coverage and indicators of missed suspicious activity.
02
Alert-to-case conversion, case aging, analyst effort and investigation rework.
03
Filing accuracy, evidence traceability, model governance and audit findings.
Case File // 06 — Technology Stack
Open to conversations on financial crime detection, Gen AI adoption and enterprise program leadership.